California Loan-Signing Appointment Checklist
A practical before, during, and after checklist for a California loan-signing appointment, including ID, package delivery, scanbacks, and where to direct loan questions.

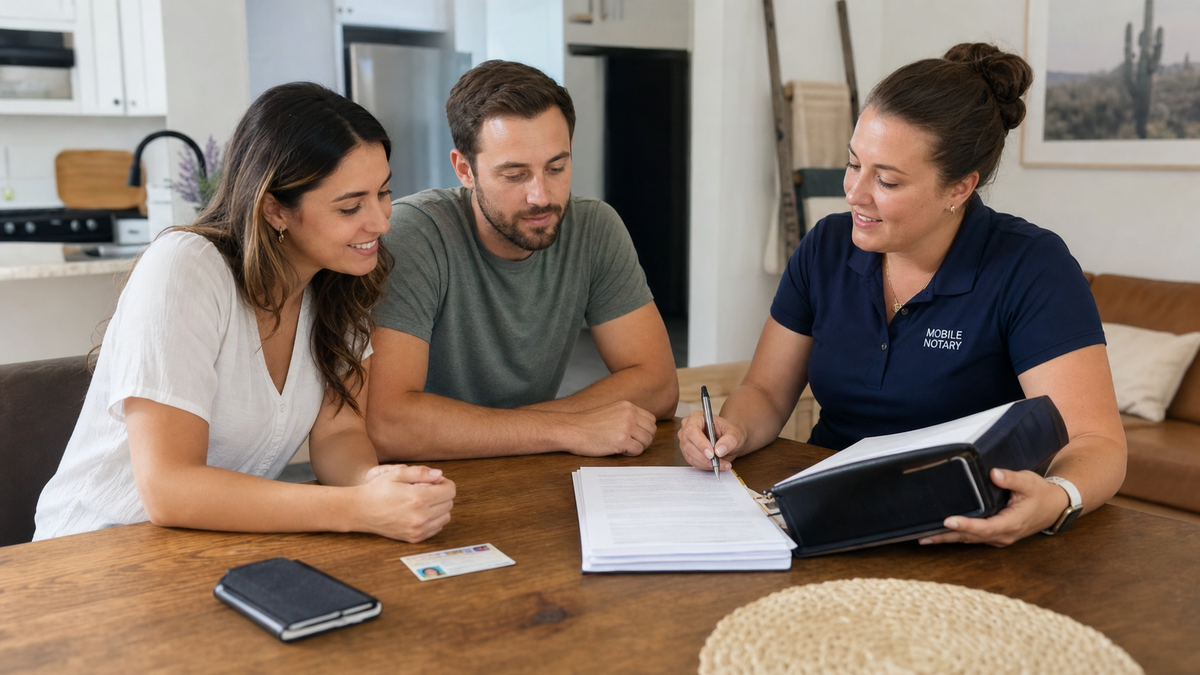
Short version: Before a California loan-signing appointment, confirm who must sign, where the document package will come from, how completed pages must be returned, and which identification each signer will use. Review loan terms with your lender or escrow officer before the notary arrives. At the appointment, the notary can manage the signing and complete required notarial acts, but questions about rates, fees, ownership, or whether you should sign belong with the lender, escrow officer, title representative, or attorney.
Quick checklist: what to have ready
- Every required signer, available for the full appointment
- Identification that meets California requirements, with names that can be matched to the package
- The complete document package—or confirmation of who will print and bring it
- Any package instructions, return label, shipping envelope, or scanback directions
- A clean table, good lighting, chairs, and enough uninterrupted time
- Your lender and escrow contacts, with direct phone numbers
- Any payment or wire instructions confirmed directly with escrow
A purchase, refinance, and seller package can look very different. If you want transaction-specific context, review the preparation details for a home-purchase signing, refinance signing, or seller-side signing.
Before the notary arrives
1. Confirm the signer list and name details
Ask escrow or the lender who must appear and which documents each person must sign. A spouse, co-owner, trustee, attorney-in-fact, or other party may have a limited role even when that person is not a borrower. Do not assume the signer list from an earlier transaction still applies.
Compare each signer’s name on the package with the identification they plan to present. If there is a meaningful mismatch, a missing middle name, a recently changed surname, or a title or trust capacity that looks wrong, contact escrow before the appointment. The notary should not edit legal or loan documents or decide how a person should sign.
2. Check identification early
California requires satisfactory evidence of identity for an acknowledgment or jurat. Common options include a California driver’s license or identification card and a U.S. passport that is current or was issued within the past five years. Certain other credentials—including qualifying out-of-state IDs, foreign passports, consular IDs, military IDs, and tribal IDs—may also work when they contain the elements required by law. The full rules appear in the current California Notary Public Handbook.
If an ID is expired, damaged, temporary, missing required details, or shows a different name, send a description to the assigned notary in advance—without emailing an unredacted ID image unless a secure method has been approved. California also allows limited credible-witness procedures, but those have specific conditions and should be arranged before the visit.
3. Review the loan before signing day
For most closed-end mortgages, the lender must provide the Closing Disclosure at least three business days before closing. The Consumer Financial Protection Bureau recommends comparing it with the latest Loan Estimate and checking the loan amount, interest rate, monthly payment, cash to close, and fees. HELOCs, reverse mortgages, and some assistance or manufactured-housing loans use different disclosures, so follow the instructions for your transaction.
Resolve unexpected terms before the appointment whenever possible. Keep the lender’s and escrow officer’s numbers nearby in case a question comes up at the table.
4. Settle the package logistics
Confirm whether the notary will bring printed documents, escrow will provide a hard-copy package, or you must print an electronic package. If you are printing, follow the sender’s instructions for paper size, scaling, page order, and single- or double-sided output. Do not remove instructions, rearrange pages, staple the package, or discard apparently blank pages unless the sender authorizes it.
Also confirm what happens afterward: courier pickup, escrow drop-off, prepaid shipment, or scanbacks before shipping. If scanbacks are required, ask who will create and send them. Keep the return label and envelope with the package. Funding, recording, and shipping cutoffs can make these details time-sensitive.
During the appointment
5. Expect identity and journal steps
Each signer should personally appear with identification. The notary records required information in a sequential journal and asks each person whose signature is notarized to sign the journal. For a deed, deed of trust, quitclaim deed, or another document affecting real property, California generally requires the signing party’s thumbprint in the journal. That is a normal fraud-prevention step, not an extra loan condition.
6. Follow the package, but pause for substantive questions
The notary or signing agent can identify signature, initial, and date lines; keep the package organized; and complete the notarial certificates called for by the documents. The notary verifies identity and performs the required notarial act—not the truth, accuracy, financial wisdom, or legal effect of the document.
If the interest rate, payment, prepayment terms, fees, cash to close, vesting, legal description, loan amount, or document purpose is unexpected, stop on that page. Call the lender or escrow officer and get an answer before continuing. The notary should not interpret the term, negotiate a change, or advise you whether to sign. If the issue requires legal advice, contact a qualified attorney.
7. Do not use a blanket rule about signing early
The safest practical approach is to leave signature and date lines blank unless the package sender instructs otherwise. Still, a document is not automatically invalid merely because it was signed before the notary arrived. For a California acknowledgment, the signer may acknowledge a signature made earlier while personally appearing before the notary. A jurat is different: the signer must take an oath or affirmation and sign in the notary’s presence. Package instructions may be stricter than the minimum notarial rule, so follow the instructions for that transaction.
After everyone signs
8. Allow time for a completion check
Before the package leaves the table, the signing agent should check it for missed signatures, initials, dates, and incomplete notarial certificates. This is a completion check, not a legal or financial review. Signers should also confirm that any promised copies are available and retain the documents the lender or escrow identifies for their records.
9. Confirm return and next-step ownership
Ask who is responsible for scanbacks, shipment, courier delivery, or escrow drop-off, and whether tracking or receipt confirmation will be provided. Do not assume signing means the loan has funded or the transaction has recorded. Those later steps are controlled by the lender, escrow, title, and county recording process. Questions about funding, recording, disbursement, cancellation rights, keys, or sale proceeds should go to the appropriate transaction professional.
Need to arrange a mobile loan-signing appointment in the Los Angeles area? Call or text (213) 933-2507 with the appointment location, signer count, document-delivery method, and return deadline.